The case for an asset-light supply chain partner
Owning sheds and trucks used to signal control. For many mid-sized businesses it now mostly means carrying fixed cost into volatile years.
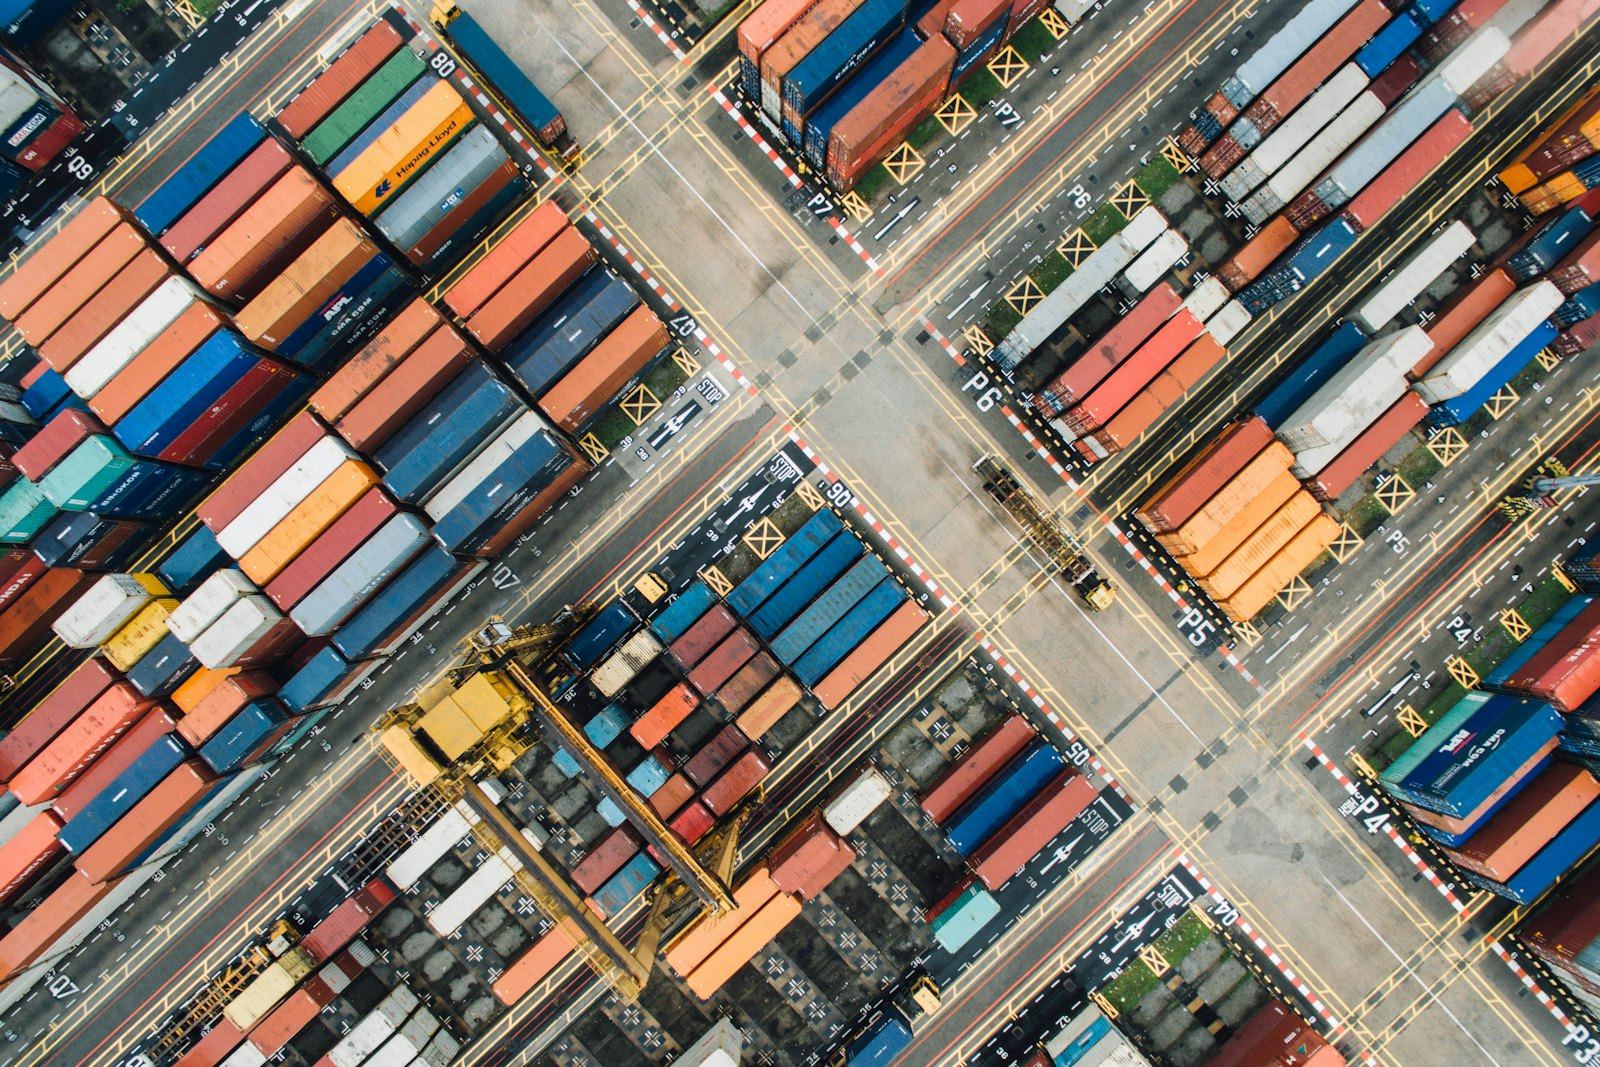
For a long time, the instinct in a growing business was to own its logistics: your own warehouse, your own fleet, your own people in branded hi-vis. It felt like control, and sometimes it certainly was.
The case for that instinct has weakened. Owning assets isn't wrong in itself. The trouble is that the cost of owning them has risen sharply while the volumes running through them have become harder to predict. When both happen at once, fixed cost becomes a liability.
What owning assets now costs
Logistics UK's Manager's Guide to Distribution Costs, published in July 2026, put the numbers bluntly. In the year to April 2026, vehicle operating costs rose by more than 12%, diesel by 36% and driver employment costs by almost 8%. Prime warehouse rents for units over 50,000 sq ft averaged £13.38 per sq ft, up 13% in the year to the first quarter. The ONS reported that services producer prices for transportation and storage were 10.7% higher in the third quarter of 2026 than a year earlier, driven by shipping rates and fuel charges linked to the conflict in the Middle East.
Space is not getting easier to find either. Savills reported a vacancy rate of 7.75% for large logistics units in the first half of 2026, with speculative development 63% below its 2022 peak. Third-party logistics providers took 38% of the space transacted.
That last figure tells you where the market is going. The specialists are taking the sheds, spreading the cost across many clients and selling capacity back by the pallet, the pick or the drop.
A worked example
The numbers below are illustrative, chosen to show the mechanics. They are not drawn from any client.
Take a distributor shipping one million units a year with total logistics costs of £6 million, or £6.00 per unit. Because it owns its warehouse and fleet, about 60% of that cost is fixed: rent, depreciation, core staff, insurance. The other 40% varies with volume.
Now suppose volume falls 20% in a weak year. Fixed costs stay at £3.6 million. Variable costs fall from £2.4 million to £1.92 million. Total cost is £5.52 million across 800,000 units, which is £6.90 per unit. Unit cost has risen 15% just because the business shipped less.
Run the same business through an asset-light model where only 25% of cost is fixed, covering orchestration, management and minimum commitments, and 75% is charged per unit. At full volume the cost is the same £6 million. At 80% volume it becomes £1.5 million fixed plus £3.6 million variable, or £5.1 million. That is £6.375 per unit, a rise of about 6%.
The difference between a 15% and a 6% rise in unit cost, in a year when volumes are already down, is often the difference between holding margin and cutting price to protect it. The same logic runs in reverse in a strong year: the owned network hits a capacity wall and has to pay premium rates for overflow, while the flexible model scales.
What asset-light actually means
The phrase gets used loosely, so a definition helps. Outsourcing to a single third-party logistics provider swaps your fixed costs for theirs, often with a long contract and minimum volumes. That can help, but you have simply changed who owns the shed.
An asset-light partner, sometimes called a fourth-party logistics provider or 4PL, sits above the carriers and warehouses. It designs the network, runs the tenders, manages performance and data across several providers, and has no fleet of its own to keep busy. Gartner published its first Magic Quadrant for 4PLs in 2025, describing them as orchestrators responsible for end-to-end visibility, governance and optimisation across carriers, brokers and technology. While the value of not owning assets is neutrality, the partner's recommendation isn't shaped by a depot it needs to fill.
When owning is still right
There are good reasons to keep assets in-house. High, stable volumes can make ownership cheaper over a long horizon. Specialist handling, such as temperature-controlled pharmaceuticals or heavy engineered goods, can be hard to buy well. And if fast, reliable delivery is the thing your customers pay you for, you may want direct control of it.
There are also costs to the asset-light route. You pay a margin to the orchestrator as well as to the providers underneath. You need someone on your side who can hold the partner to account. Transition takes time: a warehouse move or carrier change needs months of planning, and the riskiest moment is the cutover.
A few years ago, a retailer asked us to outsource its single distribution centre to a 3PL. When we modelled it, the site was well run, close to the core concentration of its stores and on a cheap long lease, so outsourcing would have added cost and margin to someone else. We advised them to keep it and fix two processes instead, which is generally not the answer a firm selling logistics would give.
The right answer for most mid-sized businesses is generally a blend of strategies. Keep the assets that are genuinely strategic, make everything else variable, and have one party accountable for the whole network's cost and service.
That is the job Convoy, our asset-light logistics company, was set up to do.
- Logistics UK: Rising logistics costs risk fuelling inflationary pressures, warns Logistics UK
- Office for National Statistics: Producer price inflation, UK: September 2026 including services, July to September 2026
- Savills: Robust H1 2026 big shed take-up driven by online retail acquisitions across the Midlands but spec development down 63% on peak and 20% on 2025
- FreightWaves: Gartner debuts 4PL Magic Quadrant as tariffs and disruption reshape logistics
More from Waterfront Ventures.
Values in practice: what Tata taught us about building a business
Tata's public record shows values working as operating rules, not wall posters. Here is what we have taken from it, and what we haven't.
Read the article →
Food service and QSR: margin pressure and the next operating model
Labour, rates, packaging and fuel are all moving at once. A briefing for operators on what has changed and where the margin can be won back.
Read the article →
Medical equipment: balancing cost, compliance and sustainability
Regulators, the NHS and input markets have all shifted in the past year. A checklist for medtech leaders on what to act on now.
Read the article →Follow us on LinkedIn.
Occasional insights from Waterfront Ventures. New articles, tools and what we are seeing across supply chains go on LinkedIn first.